ACEA, the Brussels-based association of Europe's major vehicle manufacturers, published its commercial vehicle registration figures for the first three quarters of 2026 on 28 October. New EU truck registrations rose 7.5% year on year to 245,079 units, driven by relatively strong demand for heavy trucks (+8.5%) while medium-truck registrations grew 2.5%. The wider commercial-vehicle picture was mixed: van registrations were broadly flat at 1,073,427 units, and the bus market grew 15.2% to 32,695 units. ACEA attributes the truck growth to a recovery from a low base — the market contracted sharply in 2025 — against a backdrop of rising energy prices across the continent.
The country breakdown is where the story sharpens. Poland posted the strongest gains among the major markets, with truck registrations up 20.5% over the nine months, followed by Spain at 13.2%; Germany grew 2.5%, while France declined 1.6%. Poland's momentum carried into buses as well: its bus registrations surged 68.6%, enough to make it the EU's fifth-largest bus market. In other words, the growth edge of European commercial-vehicle demand is running through Central and Eastern Europe faster than through the bloc's traditional big three — a detail that matters for anyone planning distribution, service networks or fleet supply east of the former EU border.
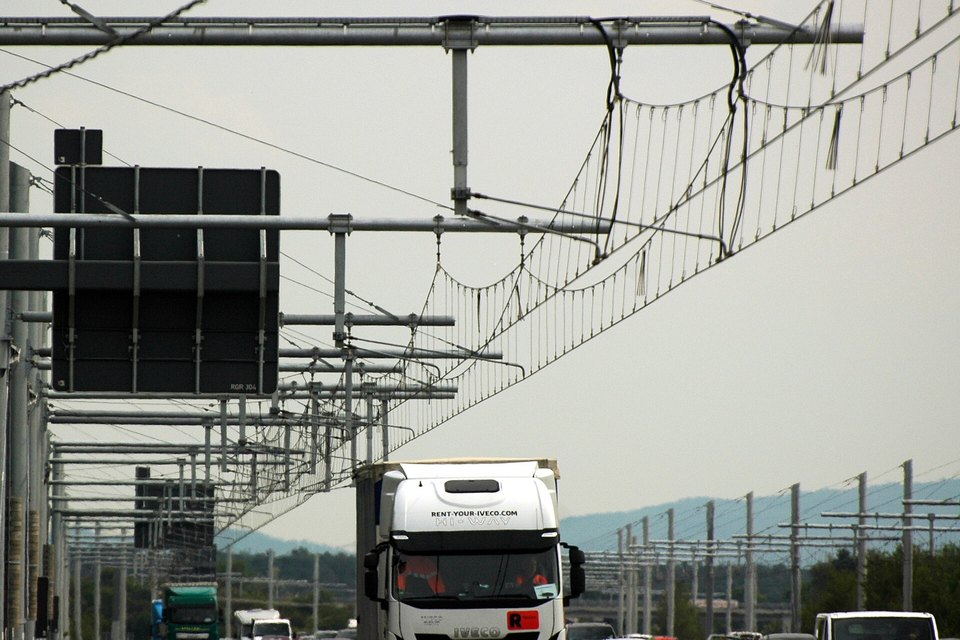
The powertrain numbers tell a second story. Electrically-chargeable truck registrations grew 49.8% in the first nine months, lifting their market share to 5.3% — but that growth was driven almost entirely by three markets: Germany (+77.2%), France (+60.2%) and the Netherlands (+57.5%), which together account for 74% of all EU electric-truck registrations. Diesel trucks, meanwhile, still take 91.7% of new registrations and actually grew 6.6% year to date. The pattern repeats in other segments at different stages: electric vans hold 14.1% of their market (up from 10.2%), and electric buses 26.4% (up from 22.1%). Electrification is real, but it is concentrated — in western hubs, in bus depots, in segments where duty cycles and incentives fit — and ACEA itself notes that uptake remains below the pace the transition requires.
For fleet operators, the figures read as replacement-cycle demand coming back. After a weak 2025, European hauliers are buying again — heavy trucks fastest, which is where deferred capex usually shows up first — while the purchase mainstream stays diesel. That combination defines a long mixed-fleet transition window: operators renew with diesel now and hedge with electric where routes and charging allow, and ACEA's own warning about the pace of electrification suggests that window will stay open well past 2027. For body builders and equipment suppliers, the recovery in heavy-truck volume is the base on which municipal and vocational demand — refuse collection, road maintenance, construction — gets rebuilt.
For truck and special-vehicle exporters, the European Union itself remains a demanding market — Euro VI emissions step, CO2 standards for heavy duty, and dense coverage from the established European manufacturers. The practical signals in this dataset sit at the edges: Central and Eastern Europe, led by Poland's 20.5% growth, is where EU truck demand is expanding fastest; diesel's 91.7% share keeps the value segment alive inside the union's periphery; and the same replacement cycle that is lifting EU registrations tends to spill outward along the freight corridors — into the Western Balkans, Moldova, Georgia and Ukraine's reconstruction pipeline — where premium European tractors are often priced out and demand concentrates on cost-competitive, specification-appropriate equipment. Exporters watching Europe should track Poland's corridors as much as the EU averages.